

Should you hold USDC in 2026? Millions of traders already park cash in USD Coin, and many now ask whether it deserves a place in a long-term portfolio. USDC promises a steady one-dollar value, fast transfers, and transparent reserves. Yet the coin also carries risks that every holder must understand before depositing real money. Yield options have grown as well, and they range from simple exchange rewards to complex DeFi strategies. This guide explains how USDC works, examines its reserves, compares yield choices, and weighs the dangers. Read on to decide whether USDC fits your goals.
What Is USD Coin (USDC) and How Does It Work?
Circle and Coinbase launched USD Coin in 2018 through the Centre consortium, and Circle now runs the coin on its own. USDC is a stablecoin, which means its price aims to match one US dollar at all times. Circle issues a new token each time a customer deposits one dollar, and it destroys a token each time a customer redeems one. This mint-and-burn process keeps the token supply in line with the dollars Circle holds. USDC runs on many blockchains, including Ethereum, Solana, Base, Arbitrum, and Avalanche. Users send it across borders in seconds and pay only small network fees. Traders use it to move in and out of volatile coins without cashing out to a bank. Developers treat it as a core building block in lending, payments, and trading apps. Businesses also use it for payroll, remittances, and treasury management. Unlike Bitcoin, USDC does not aim to grow in price, so its job is stability, not profit. Visit the official Circle USDC page to see live supply data and reserve reports.
Why Investors Hold USDC in 2026
Investors hold USDC for safety, speed, and flexibility. A stablecoin lets you step out of a falling market without leaving the crypto ecosystem. You keep your funds on a blockchain, so you can redeploy them within seconds when a good trade appears. Many users also hold USDC to avoid the high fees and slow settlement of traditional bank transfers. Freelancers and businesses in countries with weak currencies use it to protect their earnings from inflation. Exchanges list USDC on countless trading pairs, so you rarely struggle to find liquidity. Clearer regulation has also improved trust, since new US rules now set standards for stablecoin issuers. Institutions prefer USDC because it fits compliance requirements better than many rivals. Payment companies keep adding it to their networks, which expands real-world use every year. Still, holding USDC makes sense only when you understand what you gain and what you give up. You gain stability, but you give up the growth that volatile assets can offer.
How USDC Reserves Back Every Token
Reserves decide whether a stablecoin deserves your trust. Circle says it holds cash and short-term US Treasury securities to cover every USDC in circulation. It keeps most of the Treasury portion in the Circle Reserve Fund, which BlackRock manages. It holds the cash portion at regulated banks. Circle publishes regular reserve reports, and an independent accounting firm reviews them. These attestations show the reserve balance on a specific date, but they do not equal a full audit. Circle also publishes financial results as a public company, which adds another layer of outside scrutiny. Short-term Treasuries carry low risk and little price movement, so they suit a coin that promises one-dollar redemptions. Some rival stablecoins hold riskier assets such as commercial paper or loans, so the comparison matters. Check the latest reserve breakdown on Circle’s transparency page before you commit a large sum. Reserve quality changes over time, so make reviewing it a regular habit.
Yield Options When You Hold USDC
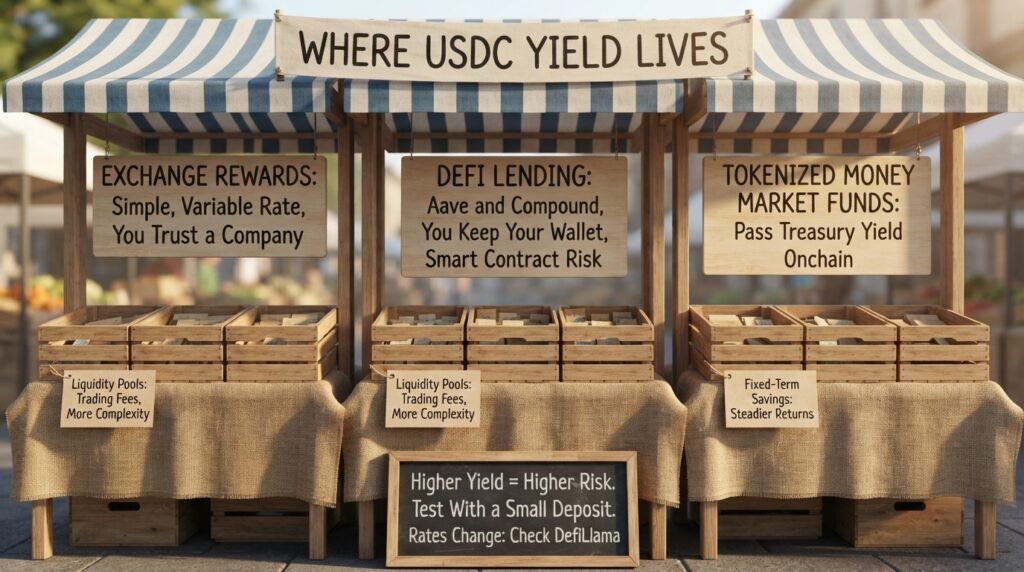
USDC itself does not pay interest, but several platforms let you earn yield on it. Centralized exchanges and apps run rewards programs, and they often pay a variable rate that moves with market conditions. DeFi lending protocols like Aave and Compound let you supply USDC to borrowers and earn interest in return. Liquidity pools on decentralized exchanges pay trading fees, although they add extra complexity and risk. Tokenized money market funds offer a third route, because they pass Treasury yields to onchain investors. Some savings products also pair USDC with fixed terms for steadier returns. Yields rise and fall with borrowing demand and interest rates, so no figure stays fixed for long. Compare live rates on DefiLlama’s stablecoin dashboard and on each platform before you deposit. Higher yield almost always means higher risk, so treat unusually generous rates with suspicion. Spread your funds across a few trusted platforms instead of placing everything in one product. Read our crypto market analysis for updates on stablecoin trends and yield changes.
Centralized Platforms vs DeFi for USDC Yield
Centralized platforms offer simplicity, because you deposit USDC and the platform handles the rest. You skip wallets, gas fees, and smart contract decisions entirely. However, you trust a company with your funds, and company failures have wiped out many customers before. The collapses of Celsius and BlockFi showed how quickly a yield platform can freeze withdrawals. DeFi protocols let you keep control through your own wallet, and their code runs in public view. You can verify the pools, track the rates, and withdraw at any time without asking permission. On the other hand, smart contract bugs and hacks can drain funds, and no support team can reverse the damage. DeFi also demands more learning, since you must manage wallets, approvals, and network fees yourself. Beginners usually start with a reputable centralized platform and small amounts. Experienced users often split funds between both worlds to balance convenience and control. Whichever route you choose, test the process with a small deposit first.
Risks You Face When You Hold USDC
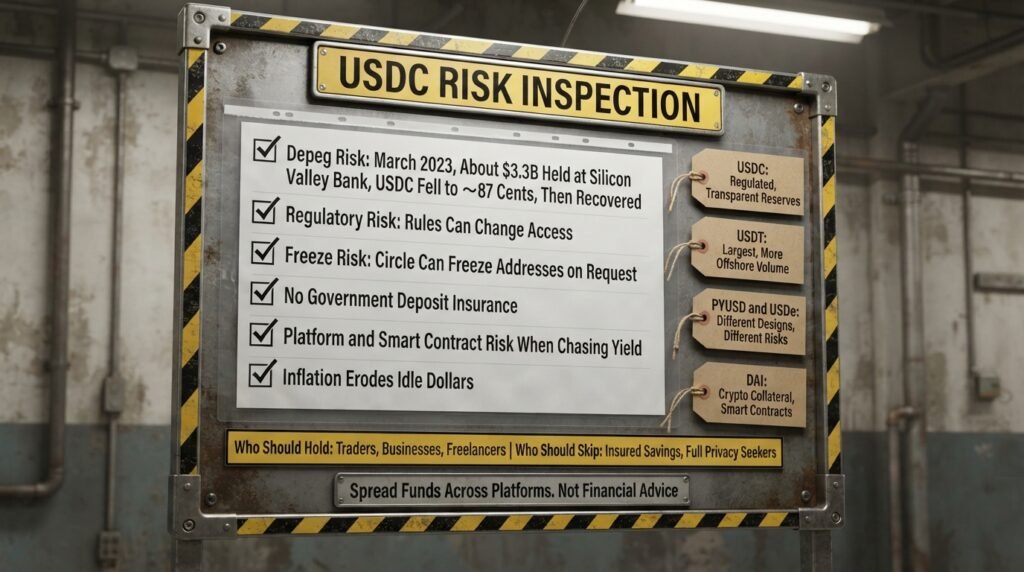
USDC looks safe, but it carries real risks. Depegging risk tops the list, because the price can drop below one dollar during a crisis. In March 2023, Circle revealed that it kept about 3.3 billion dollars at Silicon Valley Bank, and USDC briefly fell to around 87 cents. The peg recovered after US authorities protected the bank’s depositors, but the event proved that bank exposure matters. Regulatory risk also looms, since new rules can change how issuers operate and where users can access the coin. Circle can freeze USDC at specific addresses when law enforcement requests it, so you do not hold full censorship resistance. USDC carries no government deposit insurance, so you absorb the loss if the issuer fails. Smart contract and platform risks add another layer whenever you chase yield. Inflation quietly erodes your purchasing power while your dollars sit idle. Reduce these risks by spreading funds across wallets, platforms, and even different stablecoins. Read our crypto trading guides to learn basic risk control before you move large amounts.
USDC vs USDT and Other Stablecoins
Tether’s USDT remains the largest stablecoin, and USDC ranks second by market value. USDT dominates trading volume on offshore exchanges, while USDC leads in regulated markets. USDC publishes more detailed reserve information and faces tighter oversight in the United States and Europe. Tether holds a broader mix of assets and has drawn more criticism over transparency in the past. PayPal’s PYUSD and Ethena’s USDe offer other options, though they use different designs and carry different risks. USDe, for example, relies on a derivatives strategy instead of plain cash and Treasuries. Decentralized stablecoins like DAI use crypto collateral and smart contracts instead of a company’s bank accounts. Each design trades one risk for another, so no stablecoin wins on every measure. Compare supply, market share, and peg stability on CoinGecko’s USDC page. Many experienced users split holdings between USDC and one other stablecoin. This habit reduces the damage if one coin loses its peg.
Who Should Hold USDC and Who Should Skip It
USDC suits traders who need a safe parking spot between trades. It also suits businesses and freelancers who send or receive international payments. Savers who want dollar exposure onchain can use it, especially through low-risk yield products. Beginners often like USDC because exchanges and wallets support it widely. Long-term investors who want growth should treat USDC as a small cash reserve, not their main holding. People who need full privacy or censorship resistance should look elsewhere. Savers who need insured deposits should keep emergency money in an insured bank account instead. Anyone who cannot tolerate even a small chance of a depeg should hold less. A sensible approach sets a clear purpose for every dollar in USDC. Decide how much you need for trading, how much for saving, and how much you can leave in higher-yield products. Review that split every few months and adjust it as rates and rules change.
FAQs
Is it safe to hold USDC long term?
USDC ranks among the safer stablecoins because Circle backs it with cash and short-term Treasuries and publishes regular reserve reports. Still, it carries depeg, regulatory, and platform risks, and it has no deposit insurance. Spread your holdings across wallets and platforms, and keep only the amount that suits your risk level.
Does USDC pay interest by itself?
No, USDC does not pay interest while it sits in a wallet. You earn yield only when you deposit it into exchange rewards programs, DeFi lending pools, or tokenized fund products. Rates change often, and higher rates usually signal higher risk.
Can USDC lose its peg?
Yes, USDC lost its peg briefly in March 2023 after news of Circle’s exposure to Silicon Valley Bank. The coin recovered within days, but the event showed that no stablecoin offers a guarantee. Monitor reserve updates and market news, and avoid placing all your funds in one asset.
Which blockchain works best for USDC transfers?
The best chain depends on your goal. Ethereum offers the deepest liquidity and the widest app support, but fees run higher. Solana, Base, and Arbitrum give you cheaper and faster transfers for everyday use. Always confirm that the receiving wallet or exchange supports the same network before you send funds.
Final Thoughts
You should hold USDC if you want a fast, widely accepted digital dollar with transparent reserves and strong regulatory standing. The coin gives you stability, easy transfers, and several ways to earn yield. It does not give you growth, deposit insurance, or full independence from its issuer. Weigh reserve quality, platform risk, and your own goals before you deposit a large amount. Keep your funds spread out, and review your plan often as rates and rules change. Visit Crypto Fy Lab for daily crypto news and analysis. This post shares educational information only, so make your own decisions and set your own risk limits.
