

The Uniswap fee switch changed how the largest decentralized exchange rewards its token holders. For years, UNI gave holders a vote but no share of trading fees. Now Uniswap sends a slice of every enabled swap fee into a mechanism that buys UNI and burns it forever. This guide explains how the Uniswap fee switch works, how the UNI token burn operates, and what both mean for UNI holders in 2026. You will also learn the benefits, the risks, and the numbers worth tracking. For more guides like this, explore CryptoFyLab.
What Is the Uniswap Fee Switch?
The Uniswap fee switch is a governance setting that redirects part of each swap fee from liquidity providers to the protocol. Before activation, liquidity providers kept every cent of the trading fees. UNI holders only voted on proposals and earned nothing from trading activity. Reports describe the protocol share as roughly one-sixth of swap fees, which equals about 5 basis points on a typical trade. The protocol then uses that revenue to buy UNI from the open market and burn it. Here are the key points:
- Liquidity providers still earn most of the fee on every trade.
- The protocol collects its share automatically on enabled pools.
- The burn shrinks the UNI supply over time.
- Governance votes control which pools and networks pay the fee.
How the UNIfication Proposal Changed Uniswap
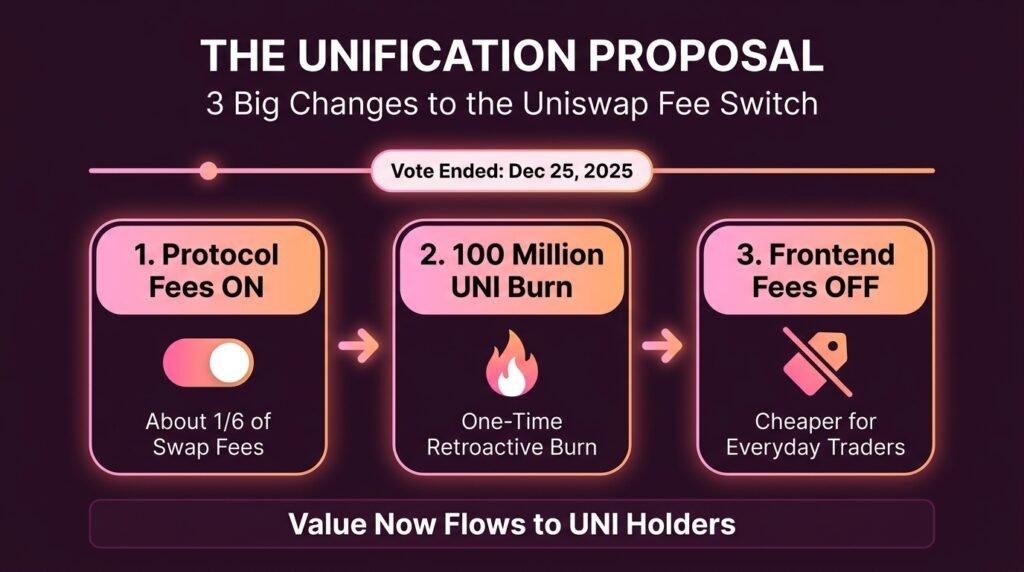
UNIfication is the governance proposal that finally flipped the switch. Years of debate preceded it, and several earlier attempts stalled. Hayden Adams, the founder of Uniswap, pushed the plan, and the community backed it. The proposal reshaped Uniswap’s economics in three ways. It activated protocol fees, it ordered a large one-time burn, and ended interface fees. The Defiant reported that Uniswap ranks among the largest fee generators in all of DeFi. That strong revenue base gave the proposal real weight. The next two sections break down the vote and the changes to the frontend.
The Vote and the 100 Million UNI Burn
The Uniswap DAO ended its vote on December 25, 2025, and the proposal passed with overwhelming support. The plan included a one-time burn of 100 million UNI tokens from the treasury. AMBCrypto explained that this burn follows a time lock before it takes effect. The burn works as a retroactive reward. It estimates the amount the protocol would have burned if the fee switch had run since the token launched. The move removed a large chunk of supply in one step. Long-term holders received the clearest signal that the community wanted to reward them. The burn does not repeat, so the ongoing buyback matters even more for the long run.
The End of Frontend Fees
UNIfication also changed how Uniswap Labs earns money. Uniswap Labs turned off the fees that its own interface charged users. The protocol now captures value at the contract level instead of the app level. This shift keeps the focus on the protocol that holders actually govern. It also makes the trading experience cheaper for everyday users. In return, the proposal gave Uniswap Labs an annual growth budget of 20 million UNI, which vests quarterly from January 1, 2026. Critics may question that budget, but supporters see it as a fair trade for removing interface fees. The structure aligns Labs with the protocol rather than with a separate fee stream.
How the UNI Token Burn Works
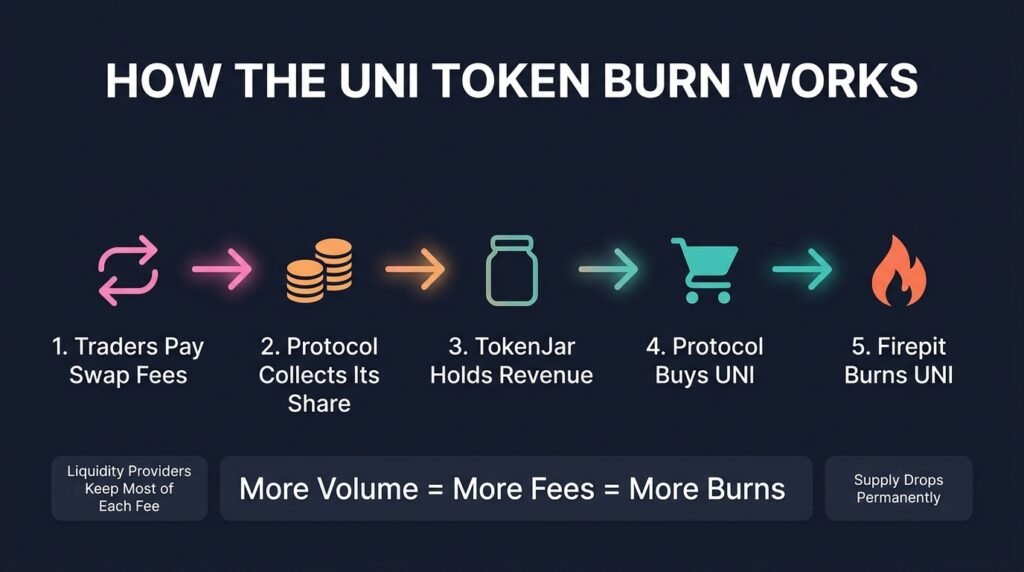
The UNI token burn follows a simple loop. Traders pay swap fees, and the protocol collects its share in special contracts. Those contracts then use the revenue to purchase UNI on the open market. The contracts send the purchased tokens to a burn address, and the supply drops permanently. This design avoids manual treasury decisions. Code runs the process, and governance only adjusts the settings. A buyback creates steady demand, while a burn removes the tokens for good. Together, they tie UNI’s supply directly to Uniswap’s trading activity. More volume means more fees, and more fees mean more burns.
TokenJar and Firepit
The fee switch routes collected fees into TokenJar contracts. TokenJar holds the revenue until the system uses it to buy UNI. The Firepit contract then handles the burn side of the process. This two-step setup keeps accounting clear and easy to audit. Anyone can watch the contracts on-chain and verify the flows. Transparency matters here because holders want proof that the burn really happens. The structure also lets Uniswap add new fee sources without redesigning the system. When the protocol adds a network or a pool type, the same contracts receive the extra revenue. That flexibility explains why the design scales so well.
How Fast the Burn Moves
Numbers vary by source, so treat every estimate with care. One report estimated an ongoing burn of roughly 4 to 5 million UNI per year, excluding the one-time 100 million burn. Another report said the protocol passed about $3.12 million in gross profit to UNI holders during the first quarter of 2026. After the July 2026 expansion, cryptonews.net reported daily revenue near $325,000. The one-time burn dwarfs the ongoing burn in size. The ongoing burn grows only when volume and fee coverage grow. Holders should track live dashboards instead of trusting a single headline figure. Gross burn and net burn also differ, so always check which one a source reports.
Why Uniswap Expanded the Fee Switch Across Networks
Uniswap does not live only on Ethereum, so a fee switch limited to one network leaves money on the table. On February 19, 2026, the team unveiled a proposal to extend fees to eight additional networks. Cryptonomist covered the plan to add a tier-based fee adapter. The adapter maps protocol fees to the existing liquidity provider fee tiers. That design removes the need for a separate vote on every pool. Revenue from layer-2 networks flows back to Ethereum, where it funds automated UNI purchases and burns. Reports also say a later proposal, executed on July 27, 2026, extended fees to v4 pools across seven networks and roughly tripled daily burn revenue. Unichain sequencer fees add another source.
What the Uniswap Fee Switch Means for UNI Holders
For UNI holders, the Uniswap fee switch creates the first direct link between protocol success and token value. Before UNIfication, a record trading month changed nothing for the token’s cash flow. Now, a busy month sends more fees into the burn. That link does not guarantee a higher price, because markets weigh many factors. UNI hit an all-time low in February 2026 even after the burn started. The fee switch gives holders a better story, not a promise. Smart holders watch both the fundamentals and the market mood. The next two sections lay out the upsides and the downsides.
Benefits for UNI Holders
The upsides are real and measurable. Holders now see these advantages:
- Supply reduction: The 100 million UNI burn and the ongoing buyback shrink the circulating supply.
- Revenue link: Trading volume now feeds directly into token demand.
- Lower friction: Turning off frontend fees makes Uniswap more attractive for traders.
- Wider coverage: Expansion to more networks increases the share of volume that pays the fee.
- Clear transparency: On-chain contracts let anyone verify the burn.
These benefits strengthen the long-term case for UNI. They do not remove short-term price swings, but they give the token a clearer purpose than it had before.
Risks UNI Holders Should Watch
Every upside carries a matching risk. Holders should weigh the following concerns:
- Small ongoing burn: The yearly burn looks modest next to the total supply.
- Volume dependence: A drop in trading volume cuts the burn directly.
- Competition: Rival exchanges can lure liquidity away with lower fees.
- Governance risk: A future vote can change or pause the fee switch.
- Regulatory pressure: Rules around fee-sharing tokens may tighten.
One analysis described UNI after the fee switch as a governance token with a real revenue link, but a smaller one than the hype suggests. That balanced view helps holders avoid unrealistic expectations.
How UNI Holders Can Track Fee Switch Progress
Smart holders measure results instead of guessing. Start with on-chain dashboards that show daily burns and protocol revenue. Compare gross burn against net burn, because the two numbers tell different stories. Follow Uniswap’s governance forum, since new proposals can change fee rates or add networks. Watch total trading volume across all supported chains, because volume drives everything. Check the circulating supply, which sat near 621 million UNI in September 202,6 according to CoinGecko data cited by Criptoview. Set a routine, such as a weekly review, and note the trend instead of daily noise. This guide offers education, not financial advice, so always do your own research before you invest.
Frequently Asked Questions
What is the Uniswap fee switch?
The Uniswap fee switch redirects a portion of swap fees from liquidity providers to the protocol. The protocol uses that revenue to buy and burn UNI.
How many UNI tokens did Uniswap burn?
Uniswap burned 100 million UNI from its treasury as a one-time retroactive burn. The ongoing buyback adds smaller burns over time.
Does the fee switch guarantee a higher UNI price?
No. The fee switch improves UNI’s fundamentals, but market conditions, trading volume, and investor sentiment still drive the price.
Do liquidity providers lose money because of the fee switch?
Liquidity providers keep most of each fee. The protocol takes only a small share on enabled pools.
Final Thoughts
The Uniswap fee switch marks the biggest change in UNI’s history. It gives holders a direct stake in Uniswap’s trading activity through a transparent buyback and burn system. The 100 million UNI burn removed a large share of supply at once, and the ongoing burn keeps working every day. Expansion across more networks should widen the revenue base further. Still, the burn depends on trading volume, and the token’s price can fall even when the fundamentals improve. Track the data, weigh the risks, and treat every number with care. For more crypto explainers, visit CryptoFyLab.
